GSTN ADVISORY | 13 OCTOBER 2026
Portal update: GSTR-9/9C for FY 2025-26 has been enabled on the GST Portal from 8 October 2026.
GSTR-9/9C for FY 2025-26 Enabled on GST Portal: Applicability & Filing Checks
GSTN has enabled GSTR-9/9C for FY 2025-26 annual return filing on the GST Portal from 8 October 2026. The advisory also asks taxpayers to ensure that all GSTR-1 and GSTR-3B returns for FY 2025-26 are filed so that the GSTR-9/9C tile becomes available.
The portal being enabled does not by itself decide whether a taxpayer is legally required to file GSTR-9 or GSTR-9C. Applicability continues to depend on the turnover thresholds and statutory exclusions under Section 44 and Rule 80.
GSTR-9/9C for FY 2025-26: Quick Applicability Answer
For FY 2025-26: registered persons with aggregate turnover up to ₹2 crore are exempt from filing the annual return under Notification No. 15/2025-Central Tax. Where aggregate turnover is above ₹2 crore and up to ₹5 crore, GSTR-9 is generally applicable but GSTR-9C is not. Where aggregate turnover exceeds ₹5 crore, the taxpayer is generally required to furnish GSTR-9 along with the self-certified GSTR-9C reconciliation statement, subject to the statutory exclusions.
Up to ₹2 Crore
GSTR-9: Exempt
Notification No. 15/2025-Central Tax exempts registered persons with aggregate turnover up to ₹2 crore from filing the annual return for FY 2024-25 onwards.
Above ₹2 Crore to ₹5 Crore
GSTR-9: Applicable
GSTR-9C: Not applicable on the ₹5 crore threshold test.
Above ₹5 Crore
GSTR-9 + GSTR-9C
Rule 80(3) requires a self-certified reconciliation statement in GSTR-9C along with the annual return, subject to statutory exclusions.
Portal Enabled Does Not Mean Filing Is Mandatory for Everyone
The GSTN advisory is a portal-enablement update. Taxpayers should separately determine whether GSTR-9 and GSTR-9C apply to them based on the turnover thresholds and exclusions under the GST law. A visible tile on the portal should not be treated as the sole test of filing liability.
What Must Be Completed Before the GSTR-9/9C Tile Is Enabled?
GSTN has specifically advised taxpayers to ensure that all GSTR-1 and GSTR-3B returns for FY 2025-26 are filed. If the GSTR-9/9C tile is not visible, this should be the first filing-status check.
- Review whether every applicable GSTR-1 for FY 2025-26 has been filed.
- Review whether every applicable GSTR-3B for FY 2025-26 has been filed.
- After completing pending periodic returns, recheck availability of the annual-return tile on the GST Portal.
- If the issue continues, GSTN has advised taxpayers to raise a ticket through the GSTN helpdesk.
Normal Due Date for FY 2025-26
Under Section 44 and Rule 80, the normal due date for the annual return and applicable GSTR-9C reconciliation statement is 31 December following the end of the financial year. Accordingly, the normal due date for FY 2025-26 is 31 December 2026, unless the Government officially extends it.
Key Statutory Exclusions to Keep in Mind
Section 44 and Rule 80 contain exclusions from the annual-return framework. These include, among others, an Input Service Distributor, persons deducting tax under section 51, persons collecting tax under section 52, casual taxable persons and non-resident taxable persons. Taxpayers should therefore check both the turnover threshold and their registration category before determining applicability.
What CAs, Tax Practitioners and Businesses Should Do Now
- Confirm applicability: identify whether turnover places the taxpayer in the up-to-₹2 crore, above-₹2 crore-to-₹5 crore, or above-₹5 crore category.
- Check filing completeness: ensure all GSTR-1 and GSTR-3B returns for FY 2025-26 are filed.
- Begin annual reconciliation: compare books, outward supplies, tax paid and ITC with the GST returns before starting the annual-return filing process.
- For turnover above ₹5 crore: plan preparation of the self-certified GSTR-9C reconciliation statement along with GSTR-9.
- Do not wait for year-end: portal enablement provides an opportunity to identify reconciliation gaps well before the normal 31 December due date.
TaxPower GST Includes GSTR-9 and GSTR-9C
GSTR-9 and GSTR-9C functionality is available in TaxPower GST. This is particularly relevant now that the FY 2025-26 annual-return forms have been enabled on the GST Portal.
CAs, tax practitioners, GST consultants and businesses using TaxPower GST can handle their annual-return work within the same GST compliance platform used for regular return workflows. Applicability and final figures should still be reviewed carefully before filing.
Frequently Asked Questions
Official GSTN Advisory Screenshot
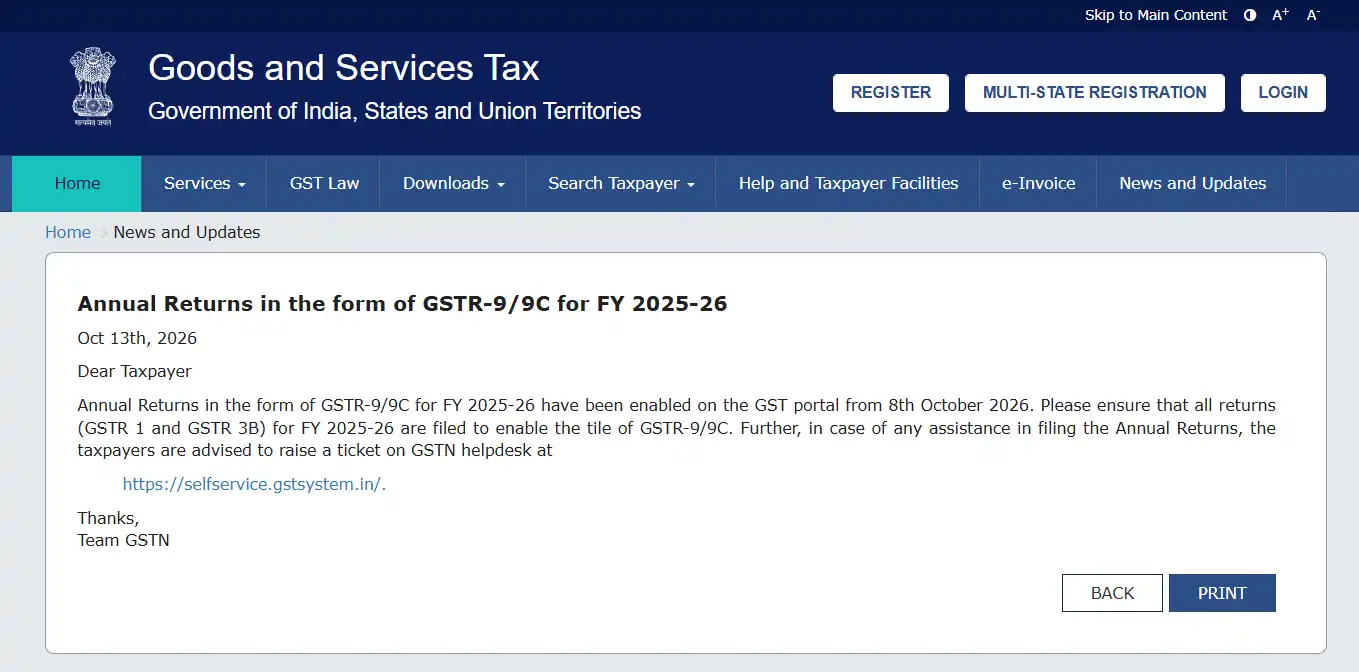
GSTN advisory dated 13 October 2026 confirming enablement of GSTR-9/9C for FY 2025-26 on the GST Portal from 8 October 2026.
Official References
- GSTN Advisory dated 13 October 2026: Annual Returns in the form of GSTR-9/9C for FY 2025-26.
- Notification No. 15/2025-Central Tax dated 17 September 2025 – annual-return exemption for registered persons with aggregate turnover up to ₹2 crore from FY 2024-25 onwards.
- Section 44 of the CGST Act – Annual Return
- Rule 80 of the CGST Rules – Annual Return and GSTR-9C
- GSTN Helpdesk
Disclaimer: This article is for general information and professional awareness. Applicability should be verified for the taxpayer’s facts, registration category and turnover before filing.
